Credit bureaus: How they can ease access to financing for businesses and individuals
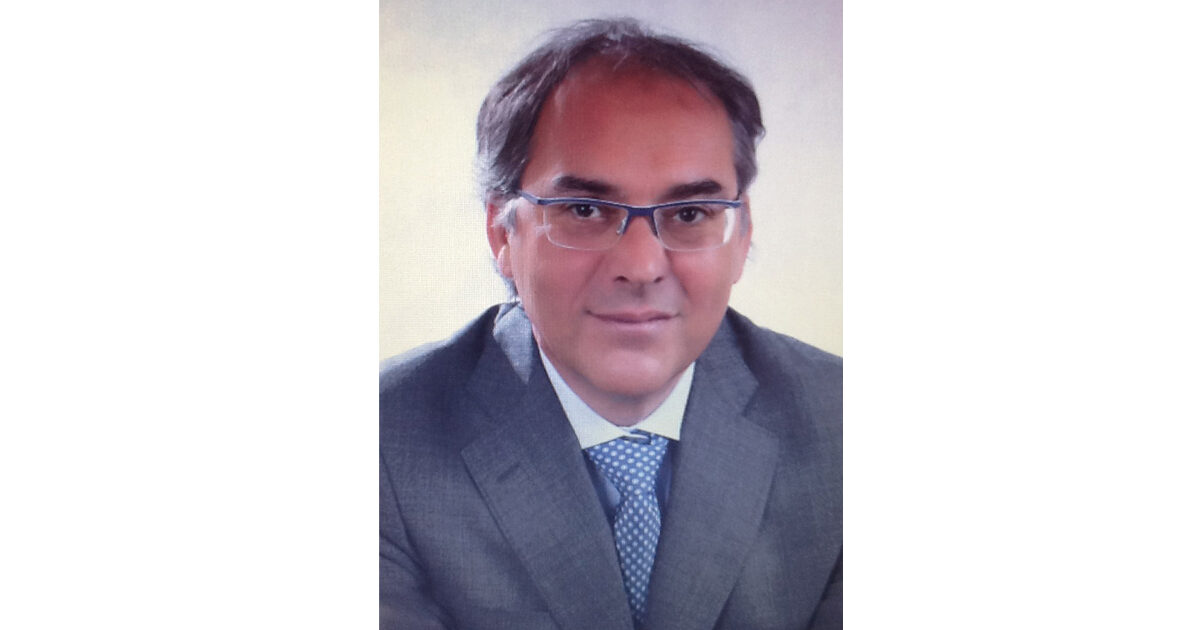
Interview with Fabrizio Fraboni, Director General of ACCIS, the European Association of Consumer Credit Information Providers
The creation of private credit bureaus is expected to bring a new link to the Albanian financial market, giving banks and other financial institutions more information to assess borrowers’ risk and to take faster lending decisions.
The bureau will not replace the Bank of Albania’s Credit Register, but will complement it with a wider range of data and analytical services.
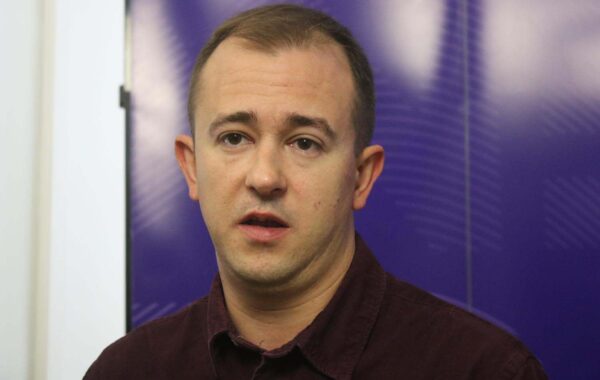
Fabrizio Fraboni, an international expert in financial infrastructure, says in an interview for “Monitor” that its role is expected to be particularly important for individuals, small businesses and new enterprises that have little credit history or limited collateral.
A documented history of payments and obligations can help these borrowers prove their ability to repay the loan, while lenders rely more on financial behaviour and less only on collateral.
Fabrizio Fraboni is an international expert with over 30 years of experience in financial infrastructure, credit assessment and risk management.
He has worked at the World Bank Group, where he supported the development of credit-reporting systems in more than 30 countries of Europe, Central Asia, Asia and Africa. He is currently Director General of ACCIS, the European Association of Consumer Credit Information Providers.
***
The World Bank Group is supporting Albania’s efforts to create credit bureaus, with the aim of expanding the possibilities to obtain financing. Why is this reform important for Albania and how will this turn into more lending possibilities for businesses and individuals?
Credit markets always face a fundamental problem: the lender knows less about the borrower than the borrower knows about himself or his business. Better information reduces this information asymmetry.
This applies especially to individuals, Small and Medium Enterprises (SMEs) and new businesses. When the lender has fuller and timely information, he can better assess the level of risk.
It also gives borrowers with solid positions the opportunity to secure financing, even when they have limited collateral or when they have no long-term relationships with the financial institution.
Albania is relatively advanced as regards credit-reporting infrastructure, since the Bank of Albania has for more than a decade successfully used the credit register.
Therefore, the creation of a private credit-reporting sector should be seen as a further and natural development of the existing data-exchange ecosystem and not as its replacement.
Among the main benefits of the private credit bureau is the ability to continuously expand the range of information available to lenders and to integrate this information into services and analytical instruments which can support a better and faster client-acceptance and lending-decision process.
The success of the private credit bureau depends on the active participation of financial institutions, especially banks as the main contributors and users of credit information.
Their commitment to effectively exchanging and using data is essential for improving risk assessment, speeding up lending decision-making and increasing access to financing.
But it should not be taken for granted that with the creation of a credit bureau everyone will automatically get more loans or that interest rates will fall immediately. The decision to approve a loan or not will remain in the hands of the financial institutions.
What changes is the quality of the information on which this decision-making rests, ensuring a more efficient risk assessment, stronger competition among lenders and a responsible increase in the possibility to obtain financing.
Can a credit bureau be an efficient business in a small market like Albania? According to EU and international experience, what would ensure that credit bureaus set affordable fees for credit reports, knowing that these fees are ultimately passed on to borrowers? Compared with the current system, what will practically change for individuals and businesses seeking credit? Who will pay for the credit report prepared by the credit bureau? Will obtaining and using credit reports create additional costs for borrowers?
A question to which, some years ago, I might perhaps have given another answer. Historically, private credit reporting has developed mostly in large economies, where the volume of credit operations could support the relatively high cost of the necessary technological infrastructure.
A considerable part of the costs are fixed: the technology, cybersecurity, data quality, compliance with legal rules and the analytical infrastructure must be maintained, regardless of whether the country has one million or twenty million borrowers.
Nevertheless, technological costs have fallen, while processing and data-storage capacity has grown greatly, especially with the development of cloud solutions. As a consequence, this sector has successfully expanded in smaller markets worldwide.
Another key driving factor is the development of international networks of specialised entities, which can exploit economies of scale in fields such as technology, product development and service administration.
The World Bank Group has supported the development of private credit-reporting infrastructures in markets similar in size to Albania in Central Asia and Asia-Pacific, while in Europe private credit bureaus successfully operate in even smaller markets, such as the Baltic states, Iceland, Cyprus and Moldova.
Nowadays, the economic model of a modern credit bureau does not depend simply on selling basic credit reports. These bureaus offer value-added services, such as credit-quality assessment, financial-crime prevention, portfolio monitoring, identity verification and decision-support instruments, which contribute significantly to the business’s sustainability.
Modern bureaus are increasingly expanding their client base, even beyond the financial sector, with products in fields such as trade credit and cross-border operations.
As regards prices, the cost of credit-reporting services is only one component of the lender’s overall credit-assessment process and is generally borne by the lender as part of operating costs.
There is also an important economic incentive here: the bureau would not benefit from an unnecessary increase in the price of the basic credit report. Since credit reporting rests on volume, a balanced pricing model will encourage wider use of the service and contribute to the bureau’s long-term sustainability.
For borrowers, I would not expect any worsening in their experience as clients.
A client with a good loan-repayment history should increasingly have the possibility to prove this history to a lender with whom he has had no previous relationship, regardless of the amount of physical collateral he has available. So, I think the client’s experience would improve and not become more complicated.
Once again, in a well-built system, the cost of obtaining credit information and the relevant services makes up only a small component of the overall cost of processing the loan application and should not be an additional obstacle to obtaining financing.
Many small businesses and individuals in Albania have little or no formal credit history. How can private credit bureaus help these borrowers obtain financing and build a financial history?
It is, in fact, one of the fields where private credit bureaus have historically given their strongest contribution.
A small business, a sole trader or an individual without a previous bank loan is often described as a person with a “thin credit file”, meaning he has little or no information regarding his debtor behaviour.
Here too there is an important economic incentive: the lack of information does not mean the borrower is risky. It only means that the lender himself does not have enough information to properly assess the risk within the credit policies.
Unfortunately, from the lender’s perspective, uncertainty itself has a cost.
An efficient credit-reporting system can gradually solve this problem by including, where legally allowed and where it is worthwhile to use, a wider package of information going beyond traditional bank loans.
Regular and on-time repayments of obligations can thus be turned into what is often called “reputation collateral”. The borrower who may not have considerable physical assets can nonetheless prove financial responsibility.
This can apply especially to young people, micro-enterprises, sole traders and SMEs.
But it must be stressed that the use of alternative data does not necessarily mean “more data”.
The data used must be accurate, appropriate and capable of enabling predictions, collected and processed under the proper legal basis, and consumers must effectively have the right to see and correct the information about them. The goal is financial inclusion and not the creation of an uncontrolled list of data.
How can the creation and functioning of private credit bureaus contribute to reducing informality in the economy, which, according to various assessments, is still considered relatively high in Albania?
The credit bureau cannot by itself solve the problem of informality, but it can create an additional economic incentive for individuals and businesses to act within the formal economy.
Formalisation gains economic value when documenting financial operations and meeting obligations on time help build a credible financial profile. For SMEs, this increases the possibility to prove borrowing capacity and creates an incentive to move from informal operations to documented transactions.
There is also a wider effect. Better information gives lenders the possibility to rely somewhat less on collateral and personal relationships and ever more on documented financial behaviour and loan-repayment capacity.
This can create a positive circle: greater formalisation brings better information; better information improves risk assessment; and a better risk assessment can increase the possibility to obtain financing from formal sources.
How should the regulatory framework balance competition and data protection in private credit bureaus, especially bearing in mind achieving the balance between market concentration and competition in a relatively small market?
This is an important question, because credit reporting is not a conventional market. In Europe we see a limited number of large operators, even in large economies like Germany, Great Britain and Italy.
Competition is important because it encourages better services, innovation and competitive prices. At the same time, credit bureaus need economies of scale and the network effect very much. The credit bureau becomes more useful the more lenders contribute data and the more borrowers are covered.
Therefore, in a market especially of Albania’s size, where an important factor is economic sustainability, a greater number of bureaus does not automatically mean more effective competition. An excessive number of entities can fragment the information, raise costs and undermine the completeness of the databases.
I think the objective of regulation should not be to maximise the number of credit bureaus licensed. On the contrary, an open market must be ensured, where only qualified operators who meet the required standards of financial sustainability, technical ability, internal governance, cybersecurity, business continuity and data protection enter and compete.
At the same time, competition can never be at the expense of data protection. Credit information is sensitive information. Strong rules are needed for data quality, permitted purposes, security, the data-retention period, the consumer’s right to see his own data, correction and dispute resolution.
Therefore, the role of the Data Protection Authority in Albania is very important: to ensure respect for the principles set out in Albanian data-protection legislation and effective supervision of the entities which process sensitive personal data.
In your opinion, does the draft law proposed by the Ministry of Economy and Innovation provide sufficient provisions for the licensing and supervision of credit bureaus and for ensuring transparency, fair competition and reasonable prices for consumers and financial institutions?
The draft law constitutes a very important step forward. If it seeks to develop a private credit-reporting sector, Albania needs a clear legal framework.
It is necessary for everyone to know the rules of the game: consumers, businesses, lenders, regulators and the credit bureaus themselves.
Who can operate as a credit bureau? What information can be collected? Who can have access to it? For what purpose? How is this information protected? What can someone do if the information held about him is inaccurate?
These are the basic issues for every modern credit-reporting system. The current draft addresses these fundamental issues and creates the basis for a balanced and transparent private credit-reporting sector.
The draft law is based on good international practices and European standards, taking the Albanian context into account as well. It includes important provisions on the rights of data subjects and dispute-resolution mechanisms, on protection from discrimination in the right to benefit from credit-reporting services, strong guarantees for data protection, and sufficient flexibility to enable innovation.
The draft law has been drawn up balancing the interests of the relevant interest groups.
How will the credit-bureau system be financed in practice? Who will cover the cost of credit reports and the relevant services: financial institutions, businesses or individuals? What measures will be taken to ensure costs remain reasonable and do not turn into an additional obstacle to borrowing?
The basic economic model is in fact quite simple. Private credit bureaus function as commercial companies. Their clients are mainly the institutions which use credit data and the relevant analytical services to take decisions, to give loans or to administer risks.
A bank, a microcredit institution or another authorised lender would pay the bureau for the credit reports, credit-quality assessments or other services it uses.
Depending on the services offered and the legal framework in force, the bureau’s services can also be used by other sectors such as telecommunications and water or electricity supply companies.
Certainly, from an economic standpoint, all the operating costs that arise for the financial institution become part of its final total-cost structure. But it would not be accurate to say that there is necessarily a specific credit-bureau fee which is passed directly and automatically to each borrower.
The question raised is whether better credit information creates more value than the cost it brings.
If a credit report gives the lender the possibility to analyse the loan application faster, to make fewer manual verifications, to detect fraud, to avoid bad loans and to assess the loan risk more accurately, then this information can lower the total cost of the lending process.
As regards the consumer, an efficient credit-information exchange infrastructure can also help soften the problem of over-indebtedness, especially when intertwined with effective financial education and training programmes.
Consumers must have the proper rights to see their credit information in a simple and financially affordable way, especially to verify its accuracy or to request corrections.
Consequently, the system should be conceived in such a way that credit reporting increases the possibility to obtain financing and does not become an additional administrative cost or obstacle to obtaining a loan.
Many European countries have had private credit bureaus for decades. Which lessons of the European experience are most current for Albania and what benefits have these systems brought in terms of the possibility to obtain financing, competition and responsible lending?
There is no single recipe for everyone and perhaps the first lesson from Europe is that there is no unique European model of credit reporting.
World experience shows that public credit registers and private credit bureaus coexist successfully, provided the respective roles and functions are clearly defined and both sides contribute to the national data-exchange ecosystem.
Public credit registers serve mainly public-policy objectives, including banking control and supervision, financial stability, microprudential and macroprudential analysis and statistical requirements, while private credit bureaus support lending decision-making, risk administration, financial-crime prevention and the development of analytical services.
Regardless of the institutional model, successful systems have almost the same basic elements: complete and accurate information, reciprocity in data exchange, clear rules on who can access data and for what purpose, strong data protection, consumer rights and advanced technology for administering and protecting data.
The second lesson is that positive information matters. A credit-reporting system is not a “black list” of borrowers who do not repay loans. Recording good behaviour in repaying all financial and, as the case may be, non-financial services gives responsible borrowers the possibility to create a financial reputation and gives lenders a much more balanced picture of risk.
Thirdly, a modern credit bureau is much more than a database. The real value is in turning data into processed information: credit quality, financial-crime prevention, portfolio monitoring, analyses and decision-support instruments.
Fourthly, the exchange of credit information empowers competition, but also helps the digital transformation of the financial sector.
A good credit-reporting system makes a client’s credit history portable and gives a lender with whom this client has no previous relationship the possibility to assess him more effectively.
Finally, and I think this has special importance for Albania, responsible lending is as important as financial inclusion. A good credit-reporting system should help lenders identify clients who can affordably take additional credit, but also those who may already be burdened with high levels of debt.
So, the objective is not simply to increase lending. The objective is lending supported by better information, at more competitive levels and in a more responsible way, for a wider part of the economy.
Komentet
Bëhu i pari që komenton!
Lini një Koment të Ri
Për t'u përgjigjur një komenti specifik, kliko butonin 💬 Përgjigju poshtë atij komenti.